YOUR FIRST-TIME HOMEBUYER’S GUIDE

Your first home.
A fresh start.

Big dreams. A few questions. A place to call your own.
Let’s make your first home feel a little less overwhelming
and a lot more possible.

Start your journey
Maria CoultA local expert. In your corner.Maria Coult, REALTOR® · Green Arc Properties
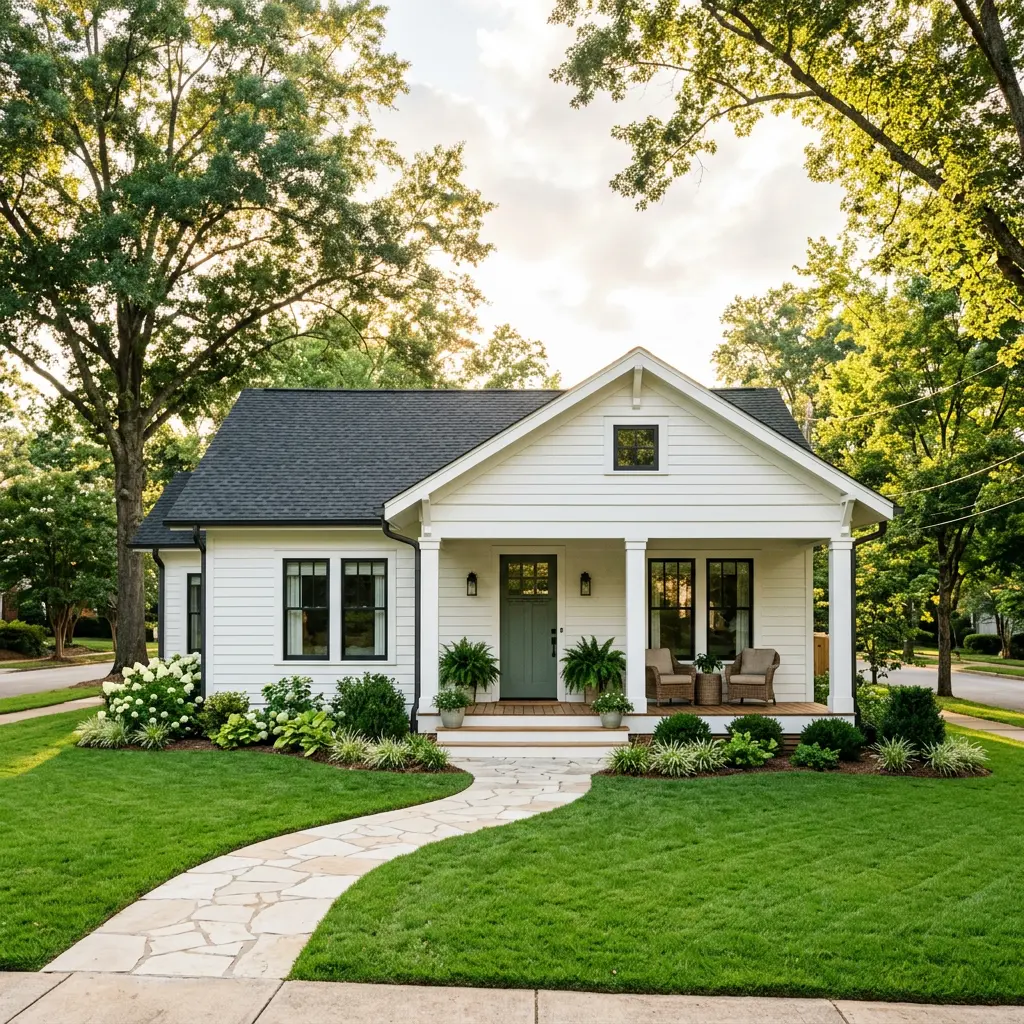
Illustration of a welcoming white Craftsman home with a green lawn, porch, and mature trees
ROOTED IN THE UPSTATE
From dreaming to doorstep.Eight simple steps. One exciting new chapter.
A new beginning looks good on you. Illustrative image
LOCAL ROOTS. REAL CONNECTIONS.

Greenville Simpsonville Fountain Inn Greer Mauldin Travelers Rest

THE ROAD TO YOUR KEYS

A little guidance.
A big new beginning.

You don’t have to figure it all out at once.
Here’s your path from “I think I’m ready” to
“This is really mine.”

8 STEPS, WITH YOU ALL THE WAY
STEP 01 / BEFORE YOU START SHOPPING

Get your finances in shape.

A confident home search starts with knowing what feels comfortable for you—not just the biggest loan a lender might approve. Give yourself time to build a financial foundation.

1 of 8

Your next little steps

  • Review your credit reports and address any errors.
  • Choose a monthly housing budget that leaves room for your life.
  • Save for your down payment, closing costs, moving, and a repair cushion.

Maria’s tipThink beyond the mortgage. Taxes, insurance, utilities, HOA fees, and maintenance belong in your monthly budget, too.

A CLEARER PICTURE OF YOUR BUDGET

Let’s talk numbers.
No surprises.

A down payment is only part of the picture. Plan for closing costs, inspections, and a little breathing room for life in your new home.

Your down paymentThe amount you put toward the purchase price.

Closing costs & prepaid expensesLender and title fees, taxes, and insurance.

A cushion for the next chapterInspections, moving, maintenance, and the unexpected.

Explore the CFPB’s homebuyer resources
YOUR STARTING-POINT CALCULATOR

What might I need upfront?

Illustrative upfront total$24,000
Down payment $15,000Closing costs $9,000

A planning illustration, not a loan quote or final cash-to-close amount. Defaults are examples, not current rates or required down payments. Excludes inspections, moving, reserves, credits, and deposits. Confirm actual costs and eligibility with your lender.

A LITTLE LOCAL KNOW-HOW

Buying in South Carolina?

There are a few things worth asking about early.

Your closing attorney

Talk with your agent and a South Carolina closing attorney about title review, closing documents, and who the attorney represents. Confirm wiring instructions by calling a trusted number—not one in an unexpected email.

Inspections & due diligence

Your signed contract sets the deadlines and cancellation terms. Ask about a general inspection, a wood-destroying organism report (CL-100), and any other checks appropriate for the property. Review all deadlines with your agent and attorney.

Taxes after you move in

Ask your county assessor about applying for legal-residence assessment and any available exemptions. Eligibility and application requirements vary; do not assume the seller’s tax bill will be your own.

YOUR HOMEBUYING TOOLKIT

A little more prepared.
A lot more confident.

Keep the essentials close.
You’ll thank yourself later.

Your document checklist

A head start for your lender conversation.

0 of 9 ready

Income

Assets

Identity & history

Your lender may request other documents. Checkmarks are for this visit only; print the guide to keep a copy. No personal documents are collected here.

KNOW YOUR OPTIONS

A loan that fits your life.

You don’t have to pick one alone. Ask your lender which programs fit your circumstances.

ConventionalA flexible starting point

Ask your lender about conventional loan options, down payment requirements, credit criteria, and mortgage insurance. Some programs are designed for eligible first-time buyers.

FHAA government-insured option

FHA-insured loans can be worth exploring if you need a lower down payment or more flexible credit criteria. Eligibility, mortgage insurance, and property standards apply. Compare the full cost with other options.

VAFor eligible military borrowers

Eligible veterans, service members, and some surviving spouses may qualify for a VA-backed loan. Ask about entitlement, funding fees or exemptions, lender requirements, and whether a down payment is needed for your situation.

USDAFor eligible locations & households

USDA programs may be available for qualifying properties and households. Location, income limits, and other requirements apply. Your lender can help check both your eligibility and the property’s.

Down payment assistanceAsk what’s available locally

Ask a lender or housing counselor about current South Carolina and local assistance programs. Funding, eligibility, repayment obligations, and program availability can change. Review the terms before relying on assistance.

Explore loan options with the CFPB
LESS JARGON. MORE CLARITY.

Words you’ll hear along the way.

Pre-approval+

A lender’s conditional assessment of what you may be able to borrow based on information and documents reviewed. It is not final loan approval.

Earnest money+

A deposit made under the purchase contract to show commitment. How it is held, applied, or refunded depends on the contract and what happens during the transaction.

Due diligence+

The period and process for researching a home and completing inspections. Your contract controls your deadlines, cancellation rights, and any fees.

Contingency+

A contract condition, such as financing or appraisal. Its exact language determines the protection and deadlines it provides.

Appraisal+

An assessment of a property’s value, commonly ordered by the lender. It is different from a home inspection and does not replace one.

Escrow account+

An account your mortgage servicer may use to hold part of your monthly payment for property taxes and insurance. Amounts can change as those bills change.

Mortgage insurance+

Insurance that protects the lender, not the buyer, on certain loans. Cost, duration, and cancellation rules depend on the loan program.

Closing Disclosure+

The document detailing your final loan terms, projected payments, and closing costs. Most covered mortgages require you to receive it at least three business days before closing.

Seller concessions+

Costs the seller agrees to pay on your behalf under the purchase agreement. Loan programs may limit the types or amounts allowed.

Title insurance+

Insurance covering certain ownership-related risks. Lender and owner policies protect different interests; ask your closing attorney what each policy covers.

Fixtures+

Items attached to the property, such as built-in appliances or lighting. Your purchase contract should clearly state what stays and what is excluded.

Cash to close+

The final amount needed to complete the purchase, accounting for the down payment, closing costs, deposits, credits, and other adjustments.
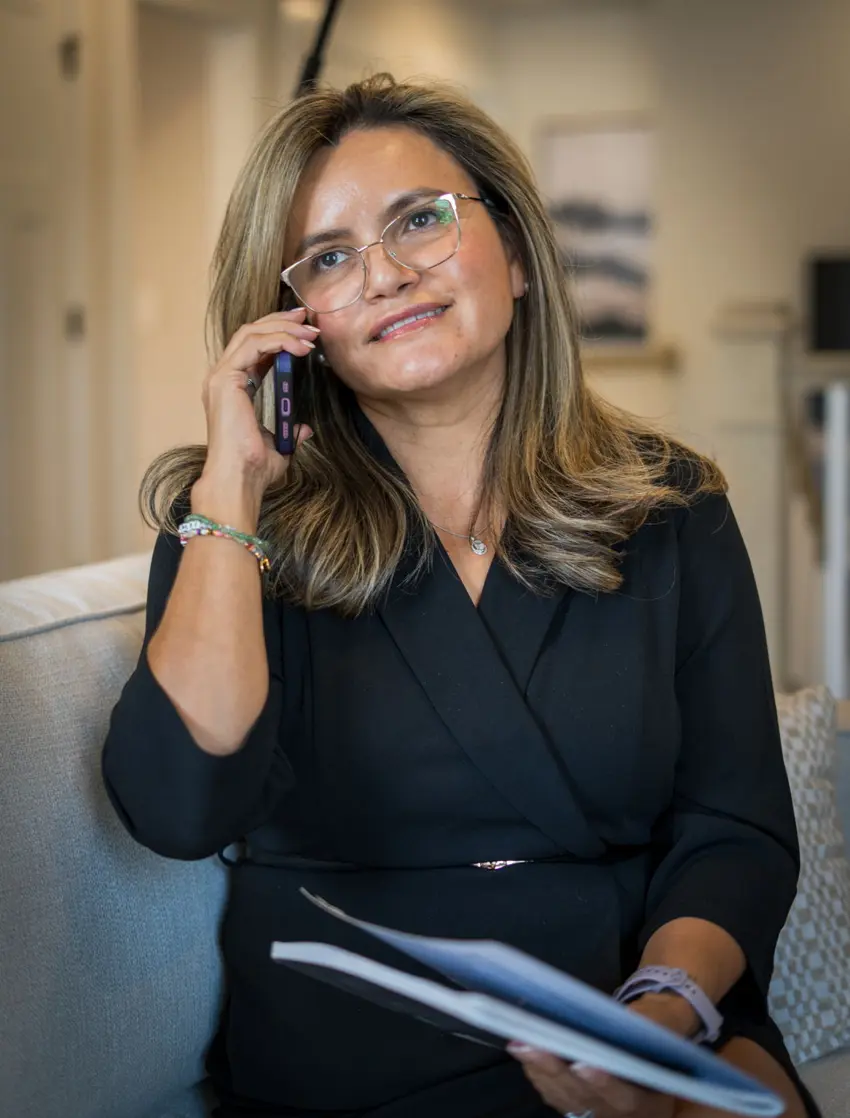
Maria Coult talking with a client by phone LOCAL EXPERTISE. GENUINE CARE.
MEET YOUR GUIDE

Hi, I’m Maria.
I’m in your corner.

Buying your first home is a lot of firsts at once. Your first pre-approval. Your first offer. Your first inspection report.

You deserve someone who makes space for your questions, explains the details in plain language, and celebrates every step with you. That’s what the Green Arc Properties team and I are here for.

Maria Coult REALTOR® · GREEN ARC PROPERTIES
Hablo español. Te acompaño en cada paso.
Let’s get to know each other
GOOD PEOPLE. LOCAL ROOTS.

You have a whole team
on your side.

Helping our Upstate neighbors buy, sell, and put down roots. Backed by Keller Williams Greenville Central.

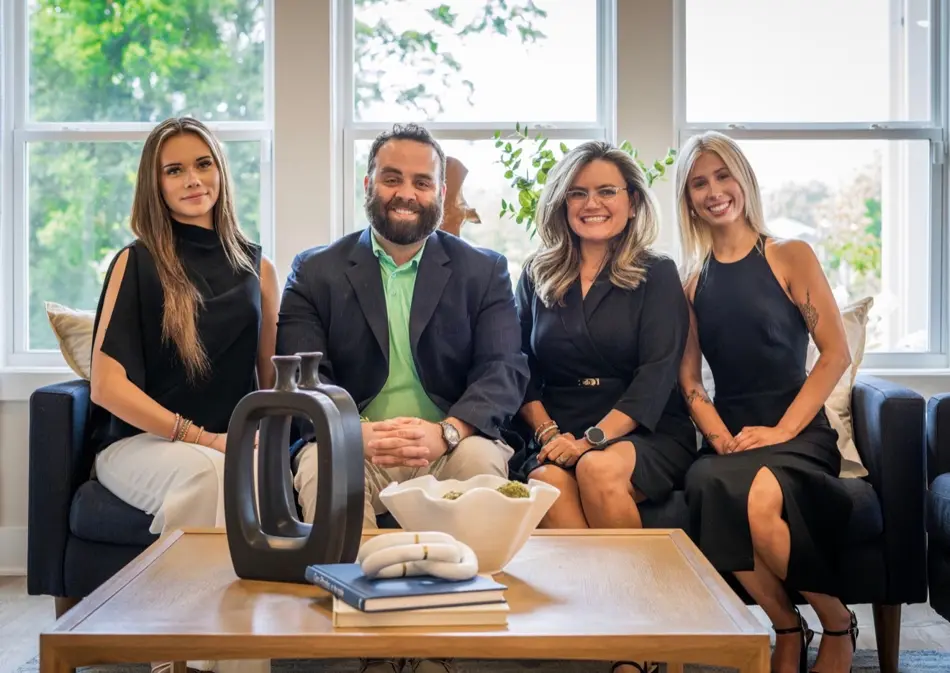
The Green Arc Properties team together in a bright living room
YOUR NEXT CHAPTER STARTS WITH A CONVERSATION

Let’s find your
place in the world.

No pressure. No question too small.
Just a friendly conversation about what comes next.

Say hello to Maria